Greenlight’s most specific documented strength comes from a parent of 6 and 8-year-olds who documents: “Very worth the $5 a month for us. Allowance is automatically withdrawn, we can transfer money back and forth instantly, other people can send them money, they can create savings goals with percentage completion bars, and set proportions to go to charity. It’s well thought out.” That specific functionality documentation — automated allowance, instant transfers, savings goals with progress tracking, charitable giving allocation — is the clearest available statement of what Greenlight delivers in daily family use. The honest caveat: a ConsumerAffairs buyer documents Greenlight deducting $75 from their account without authorization, then $200 more — and when they tried to transfer the money back to their bank account, the system wouldn’t allow it. A separate buyer’s card was deactivated, yet Greenlight continued charging $5.99 monthly for 18 months — and when their card on file expired, Greenlight charged their replacement card without being given access to it.
✅ 6 million families documented as of January 2025 — Greenlight’s scale as the leading kids’ fintech is established across independent review sources. The 6 million user base reflects genuine market adoption rather than niche appeal.
✅ Automated allowance with instant parent-to-child transfers — the core parental function praised across 5,500+ Trustpilot reviews. Automatic weekly or biweekly allowance deposits eliminate manual transfer friction; instant parent-to-child transfers for ad-hoc needs are documented as working reliably.
✅ Savings goals with percentage completion bars — a specific UX feature praised by the documented parent reviewer as genuinely engaging for children. The visual goal-tracking interface makes abstract saving concepts concrete for kids in a way that physical piggy banks or plain savings accounts do not.
✅ Charitable giving allocation — kids can set a percentage of their balance to automatically fund a designated charity. This specific feature is documented as a differentiator that adds a values-education dimension beyond basic spending and saving that competitors don’t offer at the same price.
✅ Real-time spending alerts to parents — every transaction generates an instant notification to the parent’s app, with the ability to see exactly where and how much was spent. This is the specific parental oversight feature that makes Greenlight meaningfully different from giving a child cash or a standard debit card.
✅ Store-level spending controls — parents can restrict spending to specific categories (e.g., educational, no gaming) or specific stores. The store-level granularity is documented as more specific than most competing kids’ card parental controls.
✅ Investing tier available on higher plans — the Greenlight + Invest tier allows kids to invest in ETFs from companies worth $1 billion+ with parental approval. For parents who want to introduce investing concepts alongside spending and saving, this is a specific curriculum extension that no basic savings account offers.
✅ Available anywhere Mastercard is accepted — the physical card functions as a standard Mastercard debit wherever Mastercard is accepted, making it genuinely usable for kids at retail, online, and internationally without merchant restrictions.
✅ FDIC insured through Community Federal Savings Bank — funds are held at Community Federal Savings Bank (FDIC member), providing the same federal deposit insurance as a standard bank account up to $250,000.
❌ Unauthorized account charges documented — taking $75, then $200, with no ability to transfer back — a ConsumerAffairs buyer documents Greenlight taking money from their bank account without authorization on two separate occasions, then blocking the transfer back to the bank. This is the most serious documented Greenlight failure — unauthorized fund movement from a parent’s linked bank account.
❌ Charging deactivated accounts for 18 months — charging replacement cards without consent — a ConsumerAffairs buyer who deactivated their card was still charged $5.99 monthly for 18 months. When their payment card expired, Greenlight charged the replacement card that was never provided to them — a specific documented billing control failure that constitutes unauthorized charging.
❌ Fraud on child’s card refused after 3 customer service contacts — a ConsumerAffairs parent whose child’s card had fraudulent charges contacted customer service 3 times and filed a complaint — with Greenlight refusing the refund across all contacts. For a financial product marketed for children’s safety, documented refusal to resolve fraud on a child’s account is a serious service failure.
❌ Customer service outsourced and documented as unhelpful — PissedConsumer buyers specifically document “customer service is outsourced and was horrible” as a consistent complaint. Generic responses to complaints — documented as 90% of responses being standard templates — reduce the resolution quality for specific billing and fraud disputes.
❌ Cancellation requires phone call — no self-service cancel — multiple sources document that cancelling Greenlight requires calling customer service. For a digital-first product, the absence of in-app cancellation is documented as a deliberate friction point that makes the service harder to leave than to join.
❌ Address change required 2 weeks and irrational verification steps — a ConsumerAffairs buyer who moved spent 2 weeks attempting to update their address, with customer service requiring progressively different document formats (photo → PDF) while claiming the request was already complete. For a basic account management task, this level of friction is documented as “really insane.”
❌ Cannot use Venmo, Apple Pay, or PayPal for deposits — a specific product limitation for families who use these platforms for money transfers. Deposits require a linked bank account, limiting the flexibility that some family financial workflows depend on.
Why Trust This Review
This review draws on Finder.com Greenlight debit card review (February 2026), FinanceBuzz Greenlight review (April 2026), ConsumerAffairs Greenlight (5,500+ reviews across multiple pages), PissedConsumer Greenlight (29 reviews, 2.6 stars), CardRates Greenlight review (August 2026), and Trustpilot greenlightcard.com (5,500+ reviews, 3.8/5). No affiliate relationship with Greenlight exists.
What Greenlight Gets Right — The Financial Education Case
Greenlight’s product design is the most complete kids’ financial education platform available at its price point. The combination of automated allowance, savings goals with visual progress tracking, charitable giving allocation, real-time parental spending alerts, and store-level purchase controls covers every dimension of basic financial literacy — spending, saving, giving, and supervised independence — in a single app. The investing tier on higher plans extends this into basic market participation. For parents who want their children to grow up with practical financial experience rather than abstract financial education, Greenlight’s ecosystem is the most functional available option at $4.99–$14.98/month. The parent of 6 and 8-year-olds who describes it as “well thought out” and “very worth $5/month” is the documented representative outcome for families who engage with all of the app’s features.
The Billing and Fraud Issues — The Critical Risk
The documented billing failures — unauthorized fund movements from linked bank accounts, 18-month charges to deactivated accounts, and replacement card charges without consent — are the most serious concerns in Greenlight’s review record. These are not product usability complaints; they are documented financial integrity failures that require active buyer management. The practical mitigation: use a dedicated bank account for Greenlight funding rather than your primary checking account, monitor all charges in the parent app immediately, cancel by phone call with documented confirmation of cancellation, and escalate any unauthorized charges immediately to your bank’s fraud department rather than waiting for Greenlight’s customer service resolution. The fraud dispute refusal on a child’s card — after 3 contacts — is the documented example of Greenlight’s support operation failing at the moment when a financial product’s support most needs to function.
The Competition — Where Greenlight Sits
At $4.99/month for the Core plan (up to 5 children), Greenlight is priced above some competitors (GoHenry at £3.99/month, BusyKid at $4/month annually) and below others (Famzoo at $5.99/month, Chase First Banking at $0 with a Chase checking account). The investing tier and charitable giving features are the specific functional differentiators that competitors at the same or lower price don’t offer. For families who want all features including investing, the Greenlight Max at $14.98/month is the most complete package — though the same billing control concerns apply at every tier.
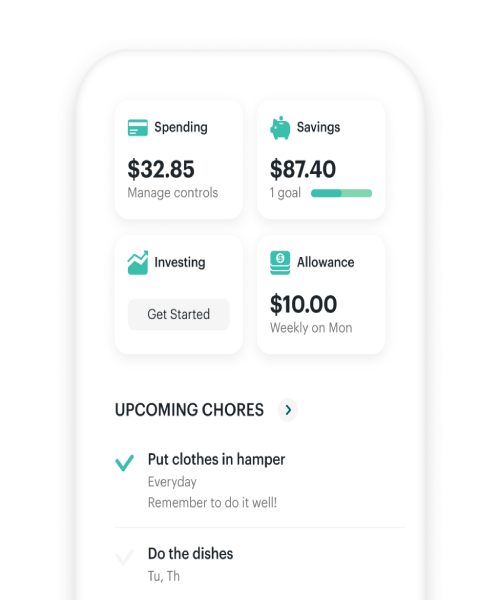
The entry plan covering automated allowance, savings goals, charitable giving, real-time spending alerts, and store-level parental controls. The right choice for families who want the core financial education features without the investing tier. Use a dedicated funding account separate from primary checking to contain any unauthorized charge risk.
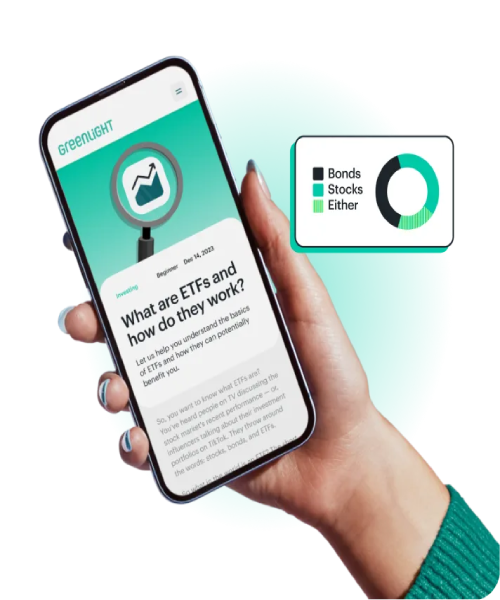
The most complete tier — adds identity theft protection for parents, priority customer service, and 1% cashback on purchases for kids. The priority customer service is the most relevant upgrade given the documented service quality concerns at the Core tier. For families who plan to use Greenlight long-term and want the best available customer service access, the Max tier’s priority support is the specific reason to upgrade.
What Customers Actually Think
“Very worth the $5 a month. No fights over coins, allowance is automatically withdrawn, transfers are instant, savings goals with completion bars, charitable giving allocation. It’s well thought out.” — CardRates verified parent reviewer
“It took $75 from my account and put it in my parental wallet, then again took $200. I did not authorize either transaction. When I tried to transfer the money back to my bank, it wouldn’t allow me to.” — ConsumerAffairs parent buyer
“Deactivated card and still charged $5.99 for 18 months following cancellation. Card on file expired and they charged my replacement card that I did not give them access to.” — ConsumerAffairs buyer
“My son’s card had fraud on it. After speaking with customer service 3 times and filing a complaint, they refused to refund my money.” — ConsumerAffairs parent buyer
“The worst customer service and irrational rules. It took 2 weeks to change my address.” — ConsumerAffairs buyer
Is It Worth It?
Buy Greenlight Core if you want the most complete kids’ financial literacy platform at $4.99/month, you use a dedicated bank account for Greenlight funding rather than your primary checking account, and you actively monitor both the parent app and your linked bank account for unauthorized charges. Cancel by phone with written confirmation and monitor your bank statement for 2+ months after cancellation.
Do not use Greenlight as your primary bank account or link your main checking account directly — the documented unauthorized charge pattern makes fund containment the essential protective measure for every Greenlight user.
Greenlight vs Competitors
Feature | Greenlight Core | GoHenry | BusyKid | Chase First | Famzoo | Copper |
Monthly Cost | $4.99 | £3.99 | $4/mo (annual) | $0 | $5.99 | $0 (basic) |
Kids per Plan | Up to 5 | 1–4 | 1–5 | 1 | Up to 4 | 1 |
Savings Goals | ✅ Visual bars | ✅ Yes | ✅ Yes | ✅ Yes | ✅ Yes | ✅ Yes |
Charitable Giving | ✅ Yes | ❌ | ✅ Yes | ❌ | ❌ | ❌ |
Investing Tier | ✅ (higher plans) | ❌ | ✅ Yes | ❌ | ❌ | ❌ |
Real-Time Alerts | ✅ Yes | ✅ Yes | ✅ Yes | ✅ Yes | ✅ Yes | ✅ Yes |
Fraud Dispute Record | ⚠️ Refusals documented | ✅ Better | ✅ Better | ✅ Strong | ✅ Good | ✅ Good |
Cancellation | ⚠️ Phone call required | ✅ In-app | ✅ In-app | ✅ In-app | ✅ In-app | ✅ In-app |
FDIC Insured | ✅ Yes | ✅ Yes | ✅ Yes | ✅ Yes | ✅ Yes | ✅ Yes |
1. Is Greenlight safe for kids?
For the financial education features — yes. For billing security — exercise active monitoring. The FDIC insurance through Community Federal Savings Bank protects deposits. The documented unauthorized charge pattern requires parents to use a dedicated funding account rather than their primary checking account and to monitor all charges actively.
2. How much does Greenlight cost per month?
Core: $4.99/month (up to 5 children). Greenlight + Invest: $7.98/month. Greenlight Max: $14.98/month. All plans are monthly subscriptions. Cancellation requires a phone call to customer service — there is no in-app self-service cancel.
3. Can Greenlight take money from my bank account without permission?
This is documented across ConsumerAffairs reviews — unauthorized transfers from linked bank accounts are a documented Greenlight complaint. Use a dedicated funding account with a limited balance rather than linking your primary checking account. Monitor the parent app and your bank statement actively and contact your bank immediately if you see unauthorized charges.
4. What is the best alternative to Greenlight?
Chase First Banking at $0/month for families with an existing Chase account is the most cost-effective alternative with a major bank’s fraud protection and customer service infrastructure. GoHenry is the strongest direct competitor in the dedicated kids’ card category with easier cancellation and better-documented fraud resolution. BusyKid includes investing at comparable monthly pricing.
5. Is Greenlight FDIC insured?
Yes — funds are held at Community Federal Savings Bank, FDIC Member, providing federal deposit insurance up to $250,000 per depositor.
Final Verdict
Greenlight delivers the most complete kids’ financial education platform in the sub-$15/month space — automated allowance, savings goals with visual progress tracking, charitable giving allocation, investing access on higher tiers, and real-time parental spending controls across all these categories are features that no competitor fully replicates at the same price point. For families who engage with all of these features, the documented parent experience is positive and the $4.99/month value is well-documented.
The billing integrity failures are non-negotiable awareness items for every prospective Greenlight parent: unauthorized fund movements from linked bank accounts, 18-month charges to cancelled accounts, and fraud dispute refusals are documented across ConsumerAffairs and must be managed proactively rather than trusted to resolve themselves. Use a dedicated funding account, cancel by phone with confirmation, and monitor bank statements for 2 months after any cancellation. These precautions preserve access to Greenlight’s genuine financial education value while containing its documented billing risks.
Scorecard
Category | Score |
Financial Education Features | 9.5/10 |
Parental Controls | 9.0/10 |
App Design & UX | 8.5/10 |
Billing Integrity | 4.0/10 |
Fraud Dispute Resolution | 4.5/10 |
Customer Service | 5.0/10 |
Cancellation Ease | 4.0/10 |
Value vs Monthly Cost | 7.5/10 |
Overall | 6.5/10 |